
Rubio’s Coastal Grill
Mill Road Capital's stewardship left Rubio's smaller, weaker, and bankrupt—twice.
Mill Road Capital purchased this fast-casual Mexican chain in 2010, amid what one trade publication called “a parade of restaurant company acquisition deals.”[i] Through its active management, MRC ultimately led Rubio’s Coastal Grill through not one, but two bankruptcies. By the time MRC walked away from its investment in 2024, both the store count and the value of the company were down by more than half.
Initially, MRC pitched itself as Rubio’s’ savior. The private equity firm had been buying Rubio’s stock on the open market and reports it had “established a strong relationship” with the publicly traded company, such that “when Rubio’s received a hostile takeover bid in 2010, Mill Road was well positioned with low cost stock and longstanding relationships to successfully take the company private as a white knight bidder.”[ii] MRC’s deal—a 14 percent premium on the previous day’s closing stock price—valued the 195-unit chain at $91 million. Rubio’s then-President and CEO was ebullient about the company’s new owner, citing MRC’s “extensive knowledge of the fast-casual segment.”[iii]
Rubio’s struggled over much of the decade, and ultimately the Covid-19 pandemic was the final straw. When Rubio’s declared bankruptcy in October 2020, it had 170 units, making it “one of the largest fast-casual chains” to do so.[iv] MRC injected Rubio’s with an additional $6 million in equity and Rubio’s obtained an $8 million loan from creditor Golub Capital Markets. Rubio’s unsecured creditors objected to the bankruptcy plan, claiming that MRC and Golub had “effectively loot[ed] the Debtors’ previously unencumbered assets, leaving nothing at all for unsecured creditors.”[v] Creditors eventually agreed to a deal for about ten cents on the dollar. Rubio’s shed $35 million in debt and exited bankruptcy in December 2020 with 150 locations.[vi] MRC owned much of Rubio’s when it emerged from this first bankruptcy.
By 2023, still owned by MRC, the chain was again struggling, and it hired a real estate company to negotiate landlord concessions.[vii] In June 2024, Rubio’s announced the closure of 48 California locations.[viii] Days later, the company announced it was filing for bankruptcy again.[ix] The company’s largest unsecured creditor, TREW Capital Management, took control of the 86-unit company using its $40 million credit bid.[x]
[i] Lisa Jennings, “Rubio’s to be sold to Mill Road for $91M,” Nation’s Restaurant News, May 10, 2010.
[ii] “Rubio’s,” Mill Road Capital, at https://www.millroadcapital.com/rubios, accessed September 4, 2025.
[iii] Lisa Jennings, “Rubio’s to be sold to Mill Road for $91M,” Nation’s Restaurant News, May 10, 2010.
[iv] Julie Littman, “Rubio’s among the largest fast casual chains to declare bankruptcy this year,” Restaurant Dive, October 27, 2020.
[v] Lori Weisberg, “Rubio’s reaches agreement to repay creditors as it prepares to emerge from bankruptcy,” San Diego Union-Tribune, December 1, 2020.
[vi] Staff, “Rubio's exiting from bankruptcy,” Fast Casual, December 23, 2020.
[vii] Reshmi Basu, “Rubio’s Coastal Grill working with Hilco to negotiate restaurant leases,” Bloomberg, January 23, 2024.
[viii] Don Lee, “Rubio’s Coastal Grill, citing rising business costs, abruptly shuts down 48 restaurants in California,” Los Angeles Times, June 3, 2024.
[ix] Lori Weisberg, “Rubio’s files for bankruptcy days after closing 48 restaurants in California,” San Diego Union-Tribune, June 5, 2024.
[x] Ben Coley, “Rubio’s to be sold to new private equity owner,” QSR Magazine, August 1, 2024.
Big Lots
Mill Road Capital chased a quick payday. Big Lots got a bankruptcy filing.
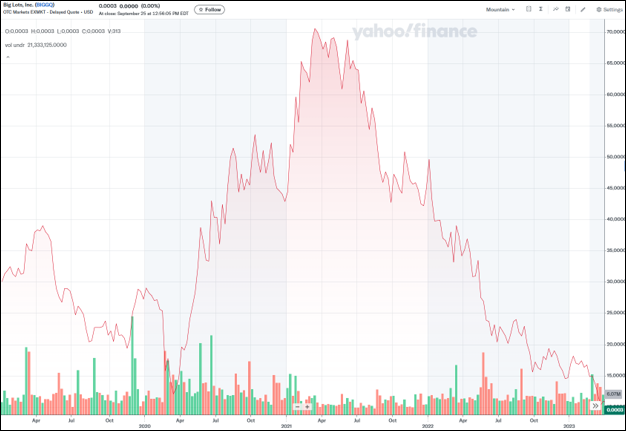
Mill Road built its stake in Big Lots during 2020,[i] a year of retail industry pandemonium. For years, ecommerce had been eating into the market share of brick-and-mortar retailers, and suddenly the industry was forced to deal with Covid shutdowns as well. MRC saw an opportunity and by the end of the year had acquired 1.7 million shares.[ii] In the second quarter of 2021, MRC sold about 15 percent of its stake when prices were near their peak.[iii] Had it sold all of its shares then, it could have tripled its investment, using its average purchase price of $20.10 per share disclosed in its first 13D on March 15, 2022.[iv]
In March 2022, with just over five percent of the company, MRC publicly urged the Board of Big Lots to sell the company, arguing the market was undervaluing the shares.[v] One analyst called MRC’s move “a short-term-minded agenda to boost stock price quickly,” and concluded that “[t]his is not shareholder activism, but it is what gives shareholder activism a bad name.”[vi] While MRC was urging Big Lots to sell itself, it was selling put and call options on Big Lots stock, short term derivatives that may have distinguished MRC’s interest from that of long term investors.[vii] By the end of 2022, MRC had sold 91 percent of its shares, having held most of it well past the peak; the stock had lost roughly two-thirds of its value in the last half of 2021 and 2022. In September 2024, Big Lots filed for bankruptcy, pointing to macroeconomic conditions.[viii]
[i] Big Lots 13D, 10/21/2022 https://www.sec.gov/Archives/edgar/data/768835/000119312522268449/d389631dsc13da.htm
[ii] Mill Road Capital 13-F, December 31, 2020, https://www.sec.gov/Archives/edgar/data/1512275/000095012321002635/xslForm13F_X01/primary_doc.xml. Note that Big Lots does not appear in MRC’s 13-F dated September 30, 2019; intervening 13-Fs are not on file.
[iii] Mill Road Capital 13-F, March 31, 2021, https://www.sec.gov/Archives/edgar/data/1512275/000095012321006936/xslForm13F_X01/primary_doc.xml and 13-F, June 30, 2021, https://www.sec.gov/Archives/edgar/data/1512275/000095012321011187/xslForm13F_X01/primary_doc.xml; Yahoo Finance stock chart.
[iv] Big Lots 13D filed by Mill Road Capital, 3/15/2022 https://www.sec.gov/Archives/edgar/data/768835/000119312522075867/d296367dsc13d.htm
[v] Staff, “Investment firm Mill Road urges Big Lots to sell itself,” Reuters, March 15, 2022.
[vi] Kenneth Squire, “Mill Road calls for a sale of Big Lots. Here’s what we might learn from the firm’s earlier deals,” 13D Monitor, April 2, 2022.
[vii] Big Lots Inc Form 13D filed by Mill Road Capital Fund III, 3/15/2022: https://www.sec.gov/Archives/edgar/data/768835/000119312522075867/d296367dsc13d.htm.
[viii] Jordan Valinsky, “Big Lots files for bankruptcy,” CNN, September 9, 2024.
Superior Industries International
The wheels came off. So did nearly $30 million in shareholder value.
Superior Industries International designs and manufactures aluminum wheels for major global car makers like GM, Ford, VW, and Toyota. One of the largest auto suppliers in the world—with four factories in Mexico and three in Poland—Superior was sanguine in the face of rising material costs, pointing to its price-adjustment clauses with its OEM customers in disclosures to investors.[i]
Mill Road built most of its stake in Superior over the course of 2021 and 2022.[ii] By the time that MRC entered into a cooperation agreement with Superior in early 2024, the private equity firm owned nearly 15 percent of Superior’s common stock, having invested over $30 million.[iii] The cooperation agreement allowed MRC to nominate a director to the Superior board; MRC Managing Director Deven Petito was the firm’s representative.
The issue of aluminum tariffs can hardly have been a surprise to Superior or MRC. President Trump had imposed new tariffs on aluminum in 2018, and by the spring of 2024, around the time Mr. Petito joined Superior’s board, both major party candidates were openly discussing a further set of tariffs on aluminum (among other things to be tariffed).[iv] In February 2025, President Trump did announce a new 25 percent tariff on imported aluminum, though the administration would go on to tinker with the rules for months.
The same Superior contract that contained the price-adjustment clause also contained language allowing customers to cancel on relatively short notice[v]—and in May 2025, Superior announced it would be losing one-third of its expected 2025 revenue.[vi]

On an earnings call, the company told investors it was engaging with lenders in a recapitalization[vii], but short-selling spiked, and in June Superior was delisted from the NYSE.[viii] In July, the company and its lenders announced a deal that all-but wiped out Superior’s equity holders, who would receive an aggregate $3.1 million in cash.[ix] Mill Road’s $30 million stake would be cashed out at under $500,000.[x]
This investment raises questions about Mill Road and Director Petito’s roles in protecting the company and its shareholders—including MRC—from risky customer contracts during years of volatile tariff policies.
[i] See, e.g., “Raw materials,” Superior Industries 10-K for the year ending December 31, 2024, p. 2, https://www.sec.gov/Archives/edgar/data/95552/000095017025034599/sup-20241231.htm.
[ii] Spreadsheet of Form 13Ds and Form 4s.
[iii] Mill Road Capital Form 13DA, January 11, 2024, https://www.sec.gov/Archives/edgar/data/95552/000119312524007550/d166450dsc13da.htm.
[iv] Katie Lobosco, “Trump wants more tariffs. His earlier trade wars cost Americans $230 billion to date,” CNN, March 18, 2024; Trevor Hunnicutt, Steve Holland and David Lawder, “Biden calls for higher tariffs on Chinese steel,” Reuters, April 17, 2024.
[v] Superior Industries 10-K for the year ending December 31, 2024, https://www.sec.gov/Archives/edgar/data/95552/000095017025034599/sup-20241231.htm. See risk factors on p. 5: “The contracts we have entered into with most of our customers provide that we will manufacture wheels for a particular vehicle model, rather than manufacture a specific quantity of products. Such contracts range from one year to the life of the model (usually three to five years), typically are nonexclusive and do not require the purchase by the customer of any minimum number of wheels from us. Therefore, a significant decrease in consumer demand for certain key models or group of related models sold by any of our major customers, or a decision by a manufacturer not to purchase from us, or to discontinue purchasing from us, for a particular model or group of models, could adversely affect our results of operations, financial condition and cash flows.”
[vi] Comments from CEO Majdi Abulaban on Superior Industries Earnings Call, May 12, 2025, https://seekingalpha.com/article/4785684-superior-industries-international-inc-sup-q1-2025-earnings-call-transcript.
[vii] Comments from CEO Majdi Abulaban on Superior Industries Earnings Call, May 12, 2025, https://seekingalpha.com/article/4785684-superior-industries-international-inc-sup-q1-2025-earnings-call-transcript.
[viii] Kurl Nagl, “Superior Industries cut from NYSE after shares plunge,” Crain’s Detroit Business, June 26, 2025.
[ix] Jack Hersch, “Superior Industries to be acquired by lenders as part of debt restructuring,” Pitchbook, July 11, 2025.
[x] Mill Road Capital 13-F, March 31, 2025, https://www.sec.gov/Archives/edgar/data/1512275/000095012325005536/xslForm13F_X02/primary_doc.xml; 4,380,940 shares is 14.7% of the common stock. 14.7% of $3.1 million is $455,700.
Noodles & Company
MRC came back for seconds. Unfortunately, so did the losses.
MRC first invested in Noodles & Company through a private placement in 2017.[i] Mill Road Capital Fund II bought 8.9 million shares—about a quarter of the company’s stock—for $31.5 million.[ii] According to the associated Securities Purchase Agreement, MRC—so long as it maintained a stake of at least ten percent in Noodles & Co.—would get the right “to designate one nominee to the Board.”[iii] MRC Senior Managing Director Thomas Lynch joined the Noodles board in April 2017. By late 2018, after a surge in the stock price, MRC had sold almost half its stake for roughly $37.5 million, recouping its investment plus a nearly 20 percent return, while retaining 11 percent of Noodles’ shares. Lynch left the board in July 2019, but the investment story continued.
In mid-2021, MRC’s remaining stake peaked at about $60 million, according to the firm’s 13F filed with the Securities and Exchange Commission.[iv] Instead of selling at a relative high, when the stock price slumped in mid-2022, MRC began to rebuild its stake. Over the next 18 months, MRC’s new fund, Mill Road Capital Fund III, acquired 2,070,043 shares for $11,197,363.16,[v] and in May 2023 Lynch rejoined the Noodles board. Shortly thereafter, reporting indicated the chain’s struggles were intensifying, as a drop in customer traffic followed an increase in menu prices.[vi] Lynch’s Board role notwithstanding, Noodles stock continued its long decline.
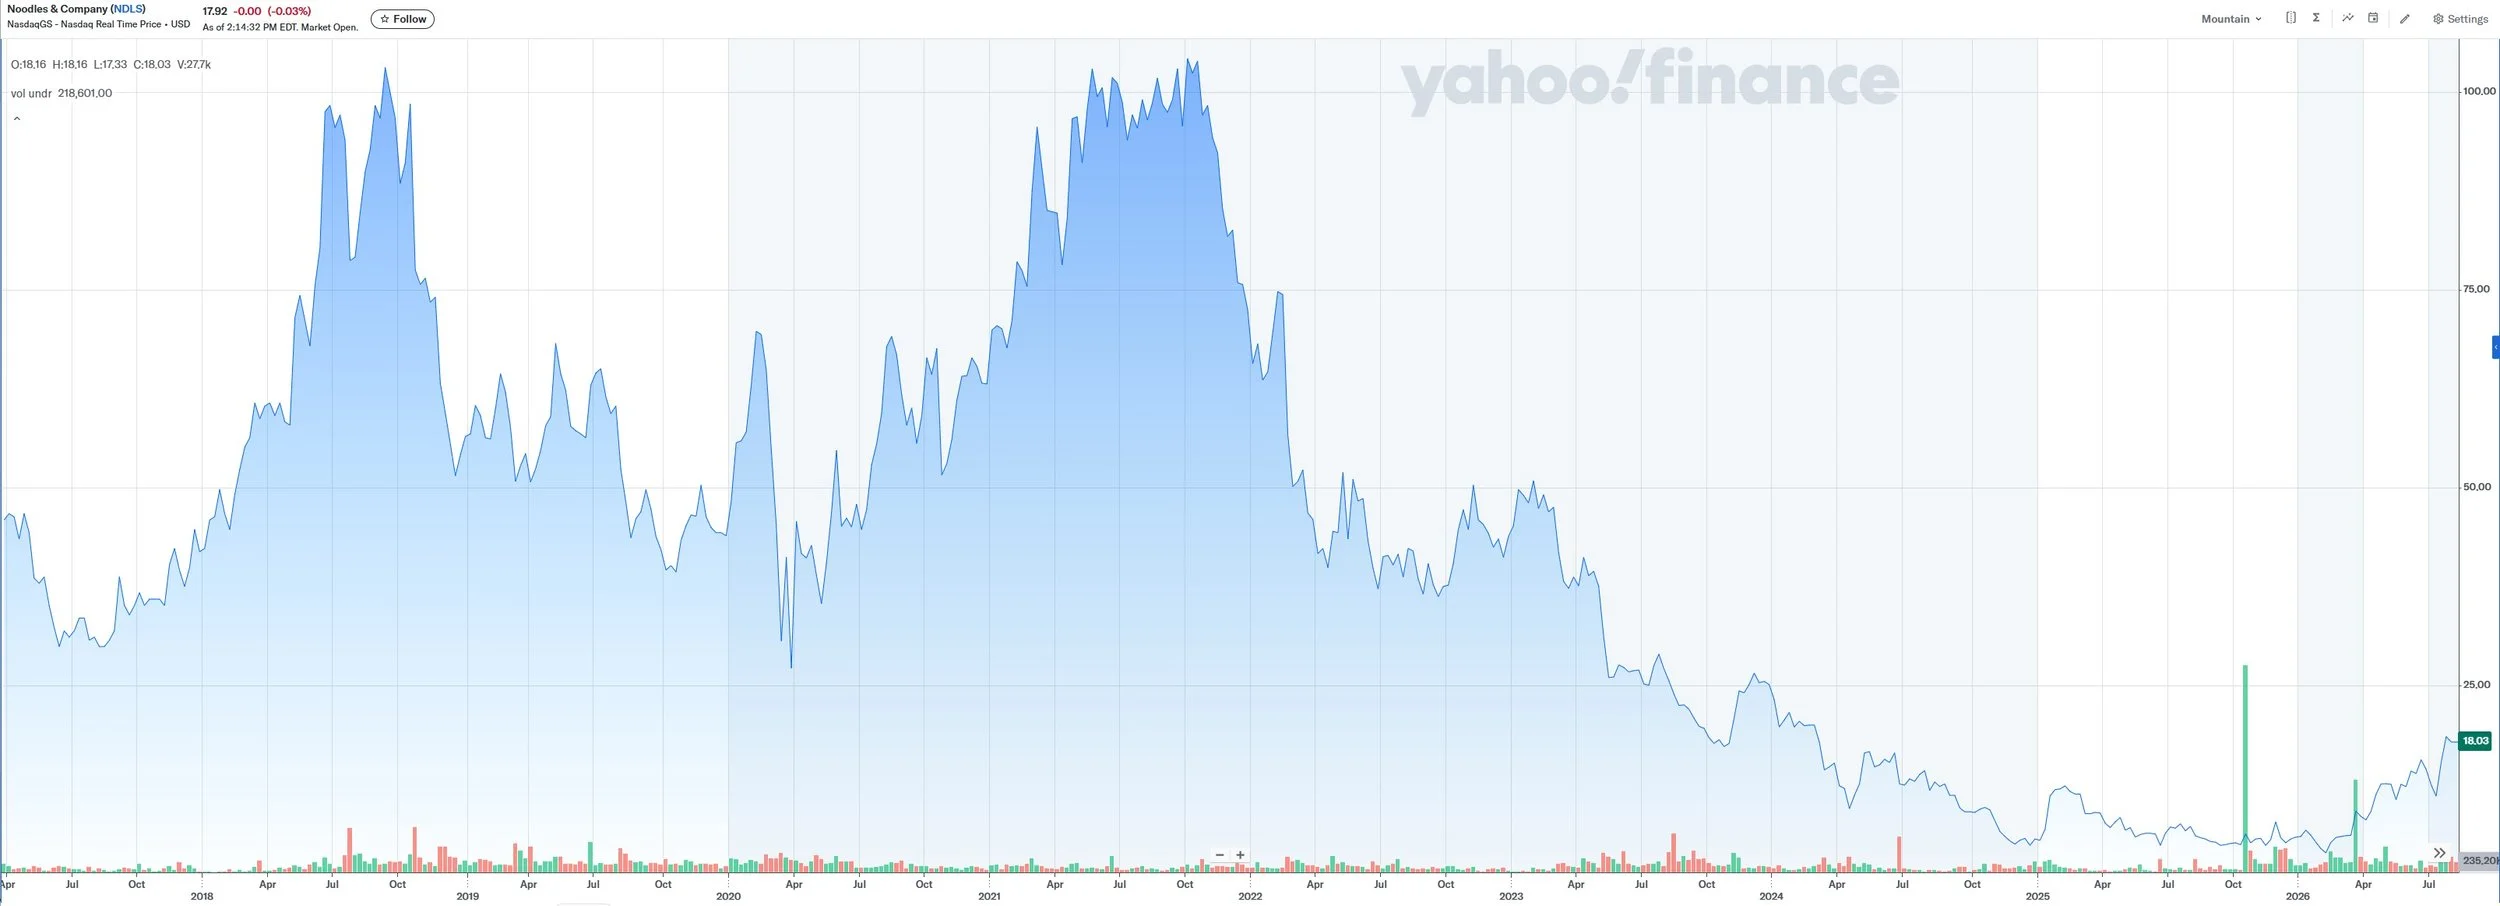
Noodles brought in new management, but the new CEO stayed only 21 months; in August 2025, the company would welcome its third CEO in under three years.[vii] A new menu was unveiled in early 2025, but it did not prevent the impending store closures—originally 9, then 21, and by August 2025 it was 49 stores to be closed, a potential 13 percent reduction in company-owned unit count.[viii]
In December 2024 the company had received a delisting notice from the Nasdaq when the Noodles share price dropped below one dollar.[ix] Noodles subsequently brought its stock price back over the threshold, but in June 2025 it slipped again, and the company received another notice of noncompliance from Nasdaq.[x] On February 18, 2026, Noodles undertook a reverse stock split at a ratio of 1:8, allowing it to continue to trade on the Nasdaq exchange.[xi]
In September 2025, the company announced that it had hired a consultant to help with a “review of strategic alternatives to maximize shareholder value.”[xii] All options seem to be on the table, including a possible sale of the company, a financial restructuring, or a simple refinancing.
In December 2025, activist investor Galloway Capital Partners urged Noodles to sell 200 company-owned restaurants to reduce debt and improve earnings per share, stating in a letter to the CEO:
“Reducing leverage to this degree would materially strengthen cash flow, eliminate perceived bankruptcy risk.”[xiii]
Mill Road Capital boasts of its long diligence process on Noodles & Company on its website:
“Mill Road first met with Noodles in 2010 and increasingly developed its understanding of the company after its 2013 IPO. Seven years of diligence positioned Mill Road to identify a balance sheet risk and approach the company with a capital solution.”[xiv]
Almost a decade later, Mill Road has transformed a solid initial return from Noodles & Company for Mill Road Capital Fund II investors into a $6 million unrealized loss for Mill Road Capital Fund III investors, or 54% decline, as of August 14, 2026.[xv] Overall, MRC’s roughly 15 percent stake is worth less than it was when MRC’s Lynch rejoined the Noodles Board in May 2023[xvi]
MRC investors are left asking: did the sunk-cost fallacy keep MRC in this investment far longer than it should have been?[xvii] Did MRC’s board role cloud its analysis about Noodles’ future course? Will a different activist investor do a better job of turning around Noodles’ fortunes?
[i] “Noodles & Company,” Mill Road Capital, at https://www.millroadcapital.com/noodles-and-company, accessed September 4, 2025.
[ii] 13D, Mill Road Capital II, dated March 13, 2017, www.sec.gov/Archives/edgar/data/1275158/000119312517093727/d319455dsc13d.htm, Also: Staff, “Noodles & Company announces private placement financing,” Reuters, March 14, 2017.
[iii] Securities Purchase Agreement by and among Noodles & Company and Mill Road Capital II, L.P., March 13, 2017, p. 19, at https://www.sec.gov/Archives/edgar/data/1275158/000127515817000020/ex101securitiespurchaseagr.htm
[iv] Mill Road Capital 13F, June 30, 2021, https://www.sec.gov/Archives/edgar/data/1512275/000095012321011187/xslForm13F_X01/0000950123-21-011187-5474.xml
[v] Mill Road Capital III Form 13D, September 13, 2023, https://www.sec.gov/Archives/edgar/data/1275158/000119312523236214/d541974dsc13da.htm “The Fund III GP, Fund III and Mr. Lynch acquired beneficial ownership of an aggregate of 2,070,043 shares of Common Stock for $11,197,363.16 using working capital from Fund III and the proceeds of margin loans”. Equates to $5.41/share, pre-reverse stock split.
[vi] Bret Thorn, “Noodles & Company to explore possible sale,” Nation’s Restaurant News, September 3, 2025.
[vii] Bret Thorn, “Noodles & Company promotes Joseph Christina from president to CEO,” Nation’s Restaurant News, August 5, 2025.
[viii] Lisa Jennings, “Noodles & Company plans to shutter up to 49 restaurants by the end of 2026,” Restaurant Business, August 13, 2025; Sarah Bregel, “Noodles & Company to close more locations: 2025 doomed list grows,” Fast Company, May 15, 2025.
[ix] Julie Littman, “Noodles & Company warned of Nasdaq delisting,” Restaurant Dive, January 3, 2025.
[x] Bret Thorn, “Noodles & Company receives delisting warning again,” Nation’s Restaurant News, June 26, 2025.
[xi] Noodles & Company Announces plans for 1 for 8 Reverse Stock Split Effective February 18, 2026, https://finance.yahoo.com/news/noodles-company-announces-plans-1-213000431.html.
[xii] Bret Thorn, “Noodles & Company to explore possible sale,” Nation’s Restaurant News, September 3, 2025.
[xiii] Noodles & Company 13DA filed by Galloway Capital Partners, 12/2/2025 https://www.sec.gov/Archives/edgar/data/1275158/000173112225001615/0001731122-25-001615-index.html
Letter: sec.gov/Archives/edgar/data/1275158/000173112225001615/e7088_ex99-1.h
[xiv] “Noodles and Company,” https://www.millroadcapital.com/noodles-and-company, accessed July 20, 2026.
[xv] MRC III paid $11,197,363 for its 283,267 Noodles shares, which are worth $5,076,145 at $17.92 per share as of 8/14/2026 close.
[xvi] 66.2 million pre-reverse split shares trading at $3.21 on May 25, 2023 were worth $20 million. After the reverse stock split, MRC’s 870,660 shares are worth $15.6 million at $17.92 per share at the August 14, 2026 close, according to Yahoo Finance.
[xvii] Definition of “sunk-cost fallacy: the phenomenon whereby a person is reluctant to abandon a strategy or course of action because they have invested heavily in it, even when it is clear that abandonment would be more beneficial.” https://www.google.com/search?q=sunk-cost+fallacy&oq=sunk-cost+fallacy
Alta Equipment
Mill Road Capital kept adding shares. The market kept subtracting value.
Alta sells, rents, and services construction and other heavy-duty equipment to a range of business customers. It typically acts as the exclusive dealer for its OEM partners in designated jurisdictions, operating in the Midwest, New York, New England, Florida, Nevada, and Canada. In its annual report, the company touts the dealership’s structure which provides “effectively no competition” because of its exclusive manufacturer relationships.[i] In recent years, Alta has been on a roll-up mission, making 16 acquisitions since 2020—and claiming to be particularly on the lookout for small family operations lacking succession plans.
Mill Road began to build a position in Alta in early 2021, and continued to buy stock on the open market, hitting about five percent ownership in mid-2023. As Alta’s stock price tumbled over 2023 and 2024, MRC added to its stake, which currently stands at just over 13 percent of the company.[ii] According to Mill Road’s filings with the U.S. Securities and Exchange Commission, Mill Road paid an average of $11.64 per Alta share.[iii]
MRC grew its position as Alta expanded and its debt grew. Alta had net losses of $80 million in 2025 and $19.5 million in the first quarter of 2026.[iv]
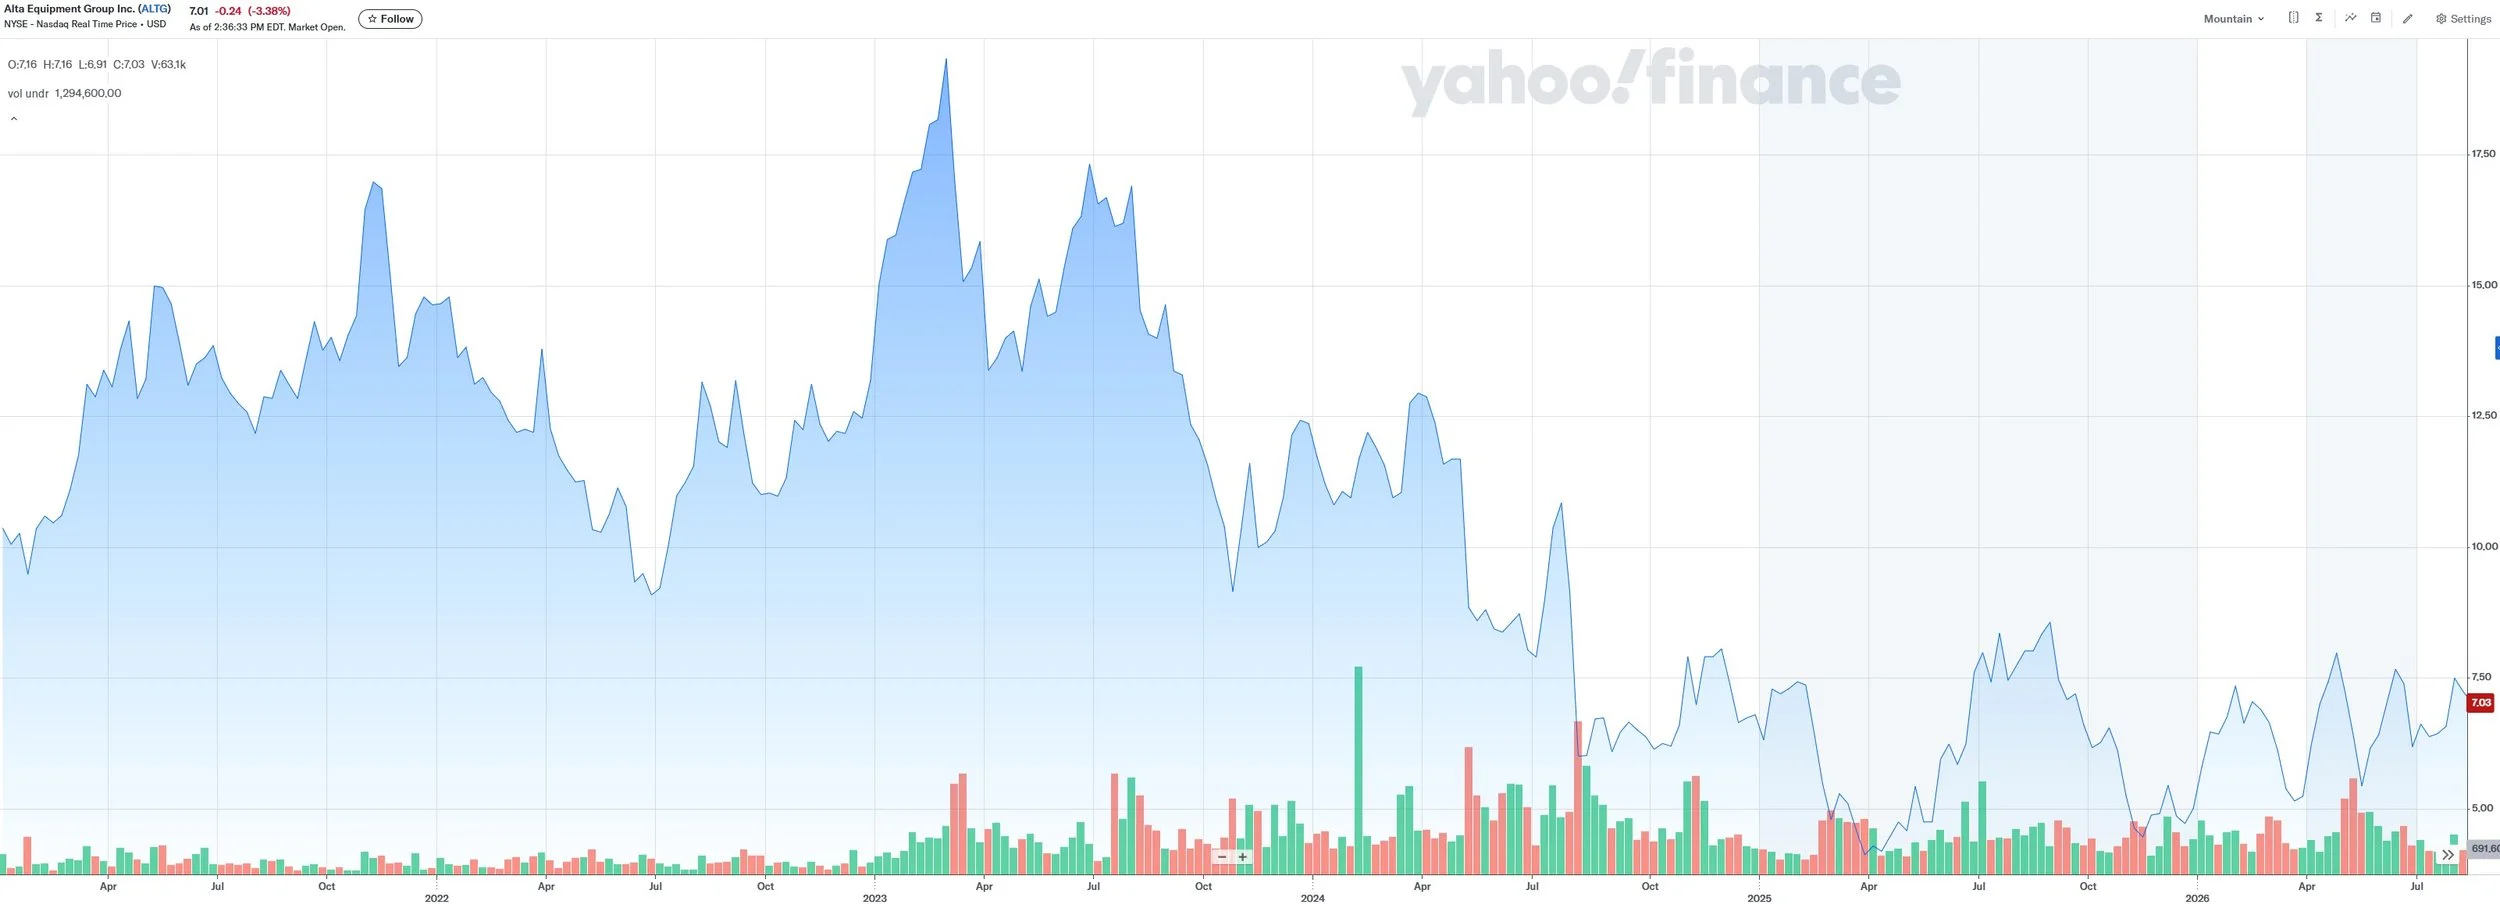
As a dealer in parts, Alta is impacted in part by tariffs. In May 2025, Alta’s CFO told investors that “any further significant increases [to tariffs], we believe, will push the situation beyond manageable and reduce customer demand.”[v] In August 2025, Alta’s CFO said that “we believe we have found a bottom,” and the stock has remained volatile.[vi] On an earnings call in early 2026, Alta CEO Ryan Greenawalt noted improvement: “Lower interest rates, tax clarity following the one big, beautiful bill, and improving customer sentiment all contributed to a more constructive environment heading into the new year… The tone in the market has improved, and we are beginning to see that translate into real demand.”[vii]
MRC’s $51 million investment in Alta is now worth approximately $31.7 million, at $7.25 per share as of the August 14, 2026 close.[viii]
In January 2026, Alta announced a Cooperation Agreement with Mill Road Capital.[ix] MRC Managing Director Deven Petito would become an Alta Board Observer, able to access all Board materials and participate in discussions, in a non-voting capacity. Whether Mr. Petito’s addition as Observer turns out to be positive for MRC or other shareholders remains to be seen.
[i] Alta Equipment Group Inc. 10-K for the year ending December 31, 2024, p. 6, https://www.sec.gov/Archives/edgar/data/1759824/000095017025033669/altg-20241231.htm.
[ii] Alta Equipment Group Inc. 10-Q for the period ending 3/31/2026: 32,532,170 shares outstanding. Mill Road Capital III owns 4,373,208 shares per Form 4 filed 3/16/26, https://www.sec.gov/Archives/edgar/data/1244666/000119312526107685/xslF345X05/ownership.xml
[iii] Mill Road Capital III 13D/A, filed 1/21/2026, https://www.sec.gov/Archives/edgar/data/1759824/000119312526019685/xslSCHEDULE_13D_X01/primary_doc.xml (“The Reporting Persons have acquired beneficial ownership of an aggregate of 4,293,208 shares of Common Stock for $50,429,841.31 using working capital from the Fund and the proceeds of margin loans under margin loan facilities maintained in the ordinary course of business by the Fund with a broker on customary terms and conditions.”); Mill Road Capital III Form 4, filed 3/13/26, https://www.sec.gov/Archives/edgar/data/1244666/000119312526105817/xslF345X05/ownership.xml (18,040 shares acquired at $6.3615 per share); Mill Road Capital III Form 4, filed 3/16/26, https://www.sec.gov/Archives/edgar/data/1244666/000119312526107685/xslF345X05/ownership.xml (58,162 shares acquired at $6.0979 per share and 3,798 shares acquired at $5.9465 per share).
[iv] Alta Equipment Group Inc. 10-K for the year ending December 31, 2025 https://www.sec.gov/Archives/edgar/data/1759824/000119312526076932/altg-20251231.htm#item8_financialstatements p. 42
[v] Alta Equipment Group Inc Earnings Call, May 7, 2025.
[vi] Alta Equipment Group Inc Earnings Call, August 7, 2025.
[vii] Alta Equipment Group Inc Earnings Call, February 26, 2026. (Ryan Greenawalt: “Lower interest rates, tax clarity following the one big, beautiful bill, and improving customer sentiment all contributed to a more constructive environment heading into the new year… The tone in the market has improved, and we are beginning to see that translate into real demand.”)
[viii] $7.25 per share according to Yahoo Finance, 8/14/26 times 4,373,208 shares of Alta as of June 30, 2026 according to Mill Road Capital 13-F.
[ix] Alta Equipment Group Inc. 8-K, January 21, 2026, https://www.sec.gov/Archives/edgar/data/1759824/000119312526019511/altg-20260121.htm.